


ASML Holding vs. Qualcomm: What Revenue Trends Tell Investors About These Semiconductor Industry Giants
ASML Holding vs. Qualcomm: What Revenue Trends Tell Investors About These Semiconductor Industry Giants
Robert Izquierdo, The Motley FoolSat, October 3, 2026 at 10:52 PM UTC
0
Key Points -
ASML currently demonstrates a stronger trajectory with consecutive periods of revenue growth, while Qualcomm is experiencing a recent contraction in its top-line performance.
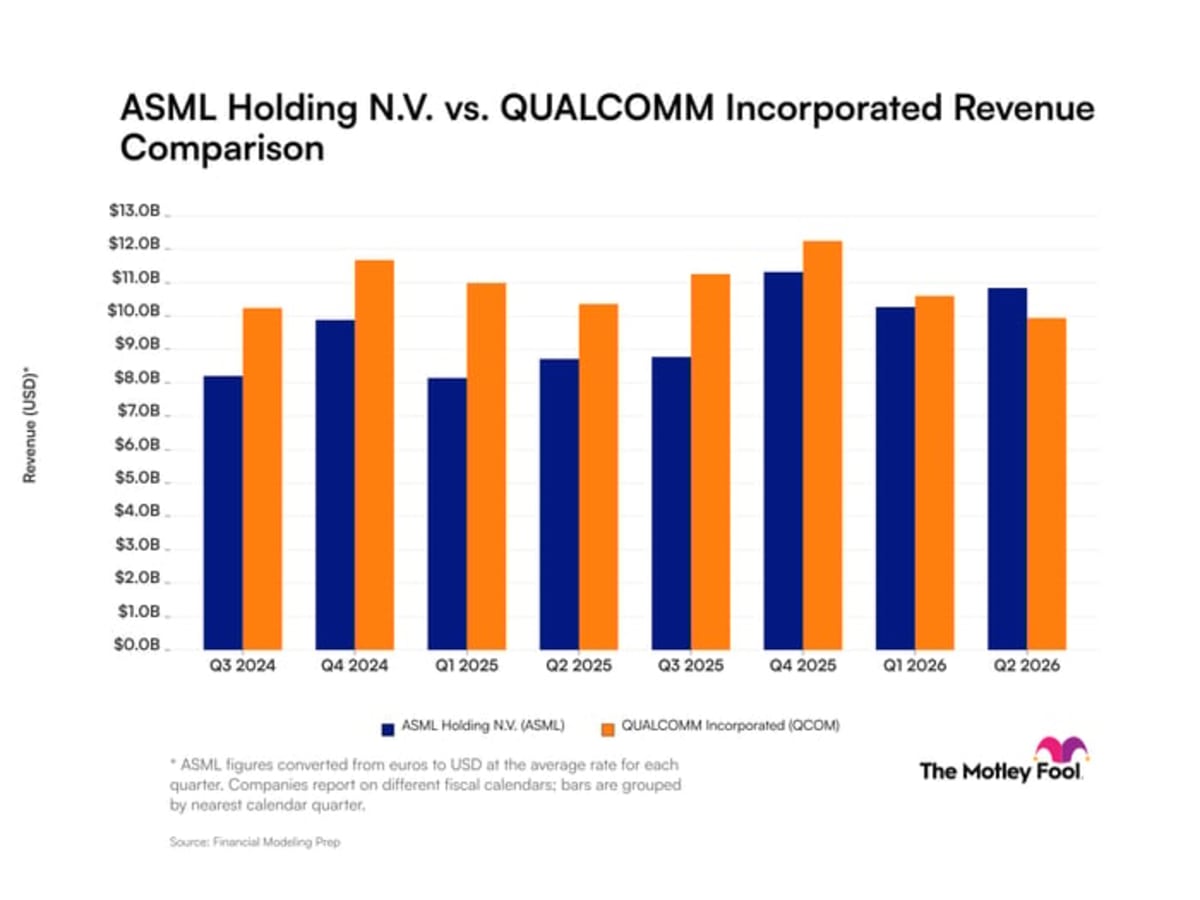
Over the last eight quarters, Qualcomm generated higher quarterly totals for the majority of the period, but ASML Holding recently surpassed it, as reported in U.S. dollars.
Investors should watch whether the two companies see their recent revenue inversion continue or if historical quarter-over-quarter patterns reassert themselves in upcoming periods.
These 10 stocks could mint the next wave of millionaires ›
ASML Holding: Consistent Revenue Growth Accelerates Recently
ASML Holding(NASDAQ:ASML) primarily generates revenue by developing, selling, and servicing advanced lithography equipment systems required by manufacturers to produce complex integrated circuits.
It recently established a collaborative initiative with Taiwan Semiconductor Manufacturing for large-format photomasks to support advanced manufacturing, while navigating broader reports of delayed data center projects affecting the timing of equipment demand.
Qualcomm: Recent Quarters Show Modest Revenue Declines
Qualcomm(NASDAQ:QCOM) primarily earns its revenue by creating integrated circuits for global wireless communication networks, supporting multimedia capabilities, and licensing its extensive portfolio of essential patented technologies.
It recently renewed a global patent license agreement with Apple, ensuring continued royalty payments through 2027, and simultaneously established a multi-generational computing infrastructure collaboration with Amazon.
Why Revenue Matters for Investors
Revenue serves as a baseline measure of total money brought into the business before accounting for operational expenses. This metric reveals whether an organization is successfully attracting customers and growing its overall business volume over time.
Quarterly Revenue for ASML and Qualcomm
Calendar quarter
ASML Holding Revenue
Qualcomm Revenue
Q3 2024
$8.2 billion (quarter ended Sept. 30, 2024)
$10.2 billion (quarter ended Sept. 30, 2024)
Q4 2024
$9.9 billion (quarter ended Dec. 31, 2024)
$11.7 billion (quarter ended Dec. 29, 2024)
Q1 2025
$8.2 billion (quarter ended March 31, 2025)
$11.0 billion (quarter ended March 30, 2025)
Q2 2025
$8.7 billion (quarter ended June 30, 2025)
$10.4 billion (quarter ended June 29, 2025)
Q3 2025
$8.8 billion (quarter ended Sept. 30, 2025)
$11.3 billion (quarter ended Sept. 28, 2025)
Q4 2025
$11.3 billion (quarter ended Dec. 31, 2025)
$12.3 billion (quarter ended Dec. 28, 2025)
Q1 2026
$10.3 billion (quarter ended March 31, 2026)
$10.6 billion (quarter ended March 29, 2026)
Q2 2026
$10.8 billion (quarter ended June 30, 2026)
$9.9 billion (quarter ended June 28, 2026)
Data source: Financial Modeling Prep. ASML Holding's figures are converted from euros to U.S. dollars. Data as of Sept. 25, 2026.
Foolish Take
Examining the revenue trends for ASML and Qualcomm reveal insights about each's business. These semiconductor industry titans are going in opposite directions in terms of sales.
ASML has delivered consistent year-over-year revenue growth. Meanwhile, Qualcomm's sales have stalled in 2026, resulting in year-over-year revenue declines. This demonstrates their unique roles within the semiconductor sector.
Advertisement
ASML is in an advantageous position. Not only is the artificial intelligence boom serving as a tailwind to its business, the company possesses a legal monopoly, since competitors have not been able to replicate ASML's advanced lithography machines used in the production of AI chips. This situation has enabled ASML to maintain reliable revenue growth over the years.
Qualcomm is experiencing falling sales because of a few different factors. Its mobile device business faces headwinds because the arrival of AI has led to steep increases in the price of components. As a result, the company's margins are under pressure while rising prices have reduced consumer demand.
Moreover, Qualcomm's modem business with Apple has eroded, adding an additional factor to its shrinking sales. The company expects to rebound by transitioning to servicing the data center market, with its Amazon partnership signaling initial success in this new line of business.
Don’t miss this second chance at a potentially lucrative opportunity
Ever feel like you missed the boat in buying the most successful stocks? Then you’ll want to hear this.
On rare occasions, our expert team of analysts issues a “Double Down” stock recommendation for companies that they think are about to pop. If you’re worried you’ve already missed your chance to invest, now is the best time to buy before it’s too late. And the numbers speak for themselves:
Nvidia:if you invested $1,000 when we doubled down in 2009,you’d have $608,222!*
Apple: if you invested $1,000 when we doubled down in 2008, you’d have $63,654!*
Netflix: if you invested $1,000 when we doubled down in 2004, you’d have $361,650!*
Right now, we’re issuing “Double Down” alerts for three incredible companies, available when you joinStock Advisor, and there may not be another chance like this anytime soon.
See the 3 stocks »
*Stock Advisor returns as of October 3, 2026.
Robert Izquierdo has positions in ASML, Amazon, Apple, Qualcomm, and Taiwan Semiconductor Manufacturing. The Motley Fool has positions in and recommends ASML, Amazon, Apple, Qualcomm, and Taiwan Semiconductor Manufacturing. The Motley Fool has a disclosure policy.
Source: “AOL Money”
