


Qualcomm Stock Has an Opportunity Investors May Be Underestimating
Qualcomm Stock Has an Opportunity Investors May Be Underestimating
Vandita JadejaSun, September 27, 2026 at 5:00 PM UTC
0
QualcommQuick Read -
QCOM is rated BUY with a $228 price target as the market underprices non-handset revenue guided to grow over 60% in fiscal 2027.
Apple's modem pullback could cut QCOM's Apple revenue in half, while Marvell's comparable valuation on less revenue suggests $228 may be conservative.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Qualcomm (NASDAQ:QCOM) is building a data center franchise that management believes can hit $15 billion in revenue by fiscal 2029. That opportunity is not fully priced in.
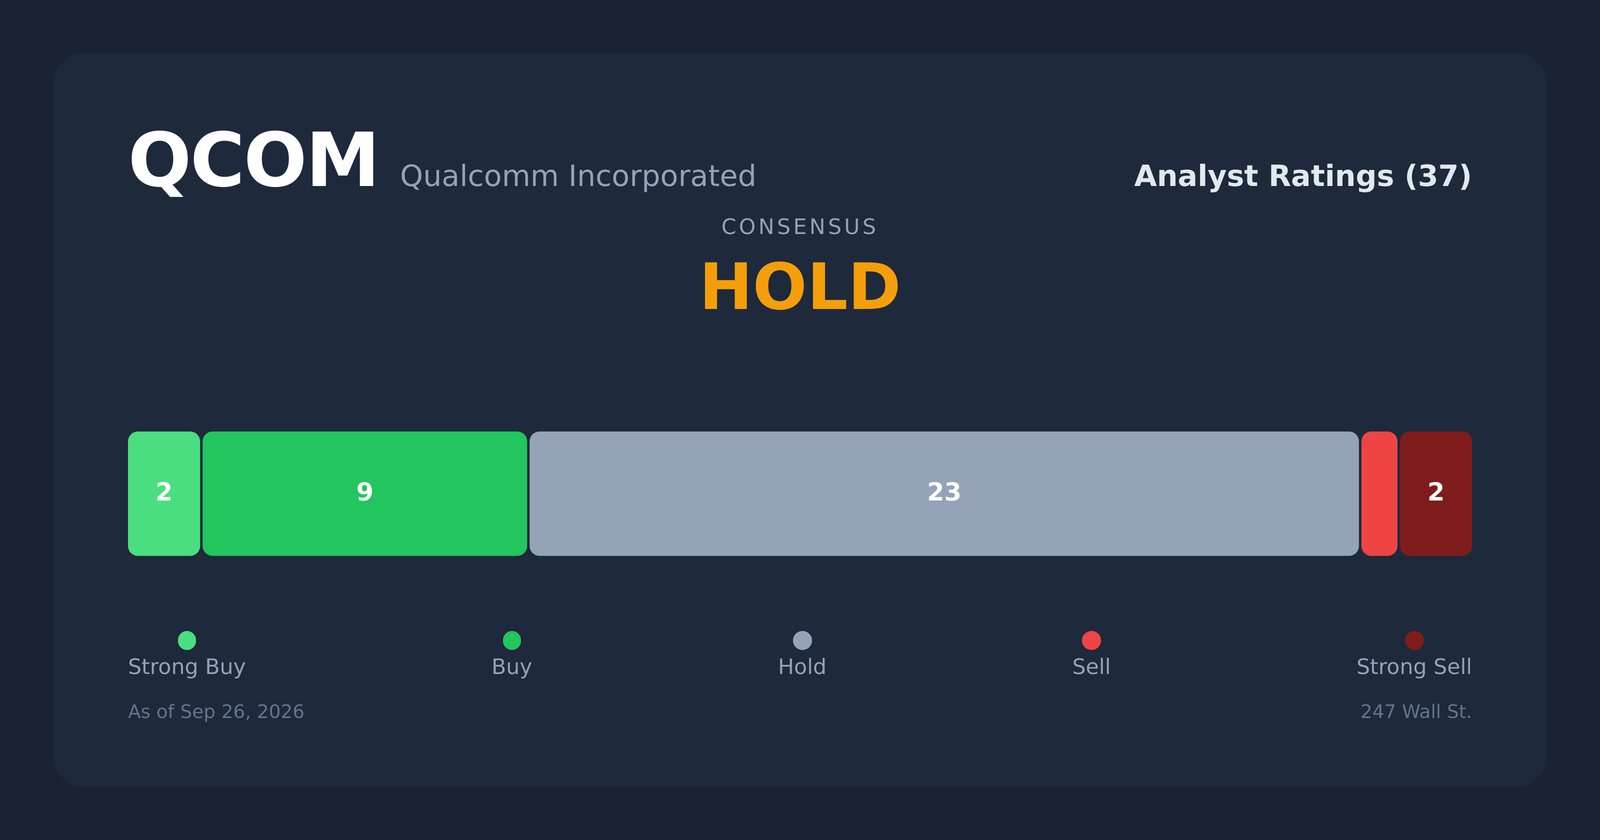
Our 24/7 Wall St. price target for Qualcomm is $228.68 over the next 12 months, implying 16.27% upside from $194.38. We rate the stock a buy with 90% confidence.
24/7 Wall St. Price Target Summary
Metric
Value
Current Price
$194.38
24/7 Wall St. Price Target
$228.68
Upside
16.27%
Recommendation
Confidence Level
90%
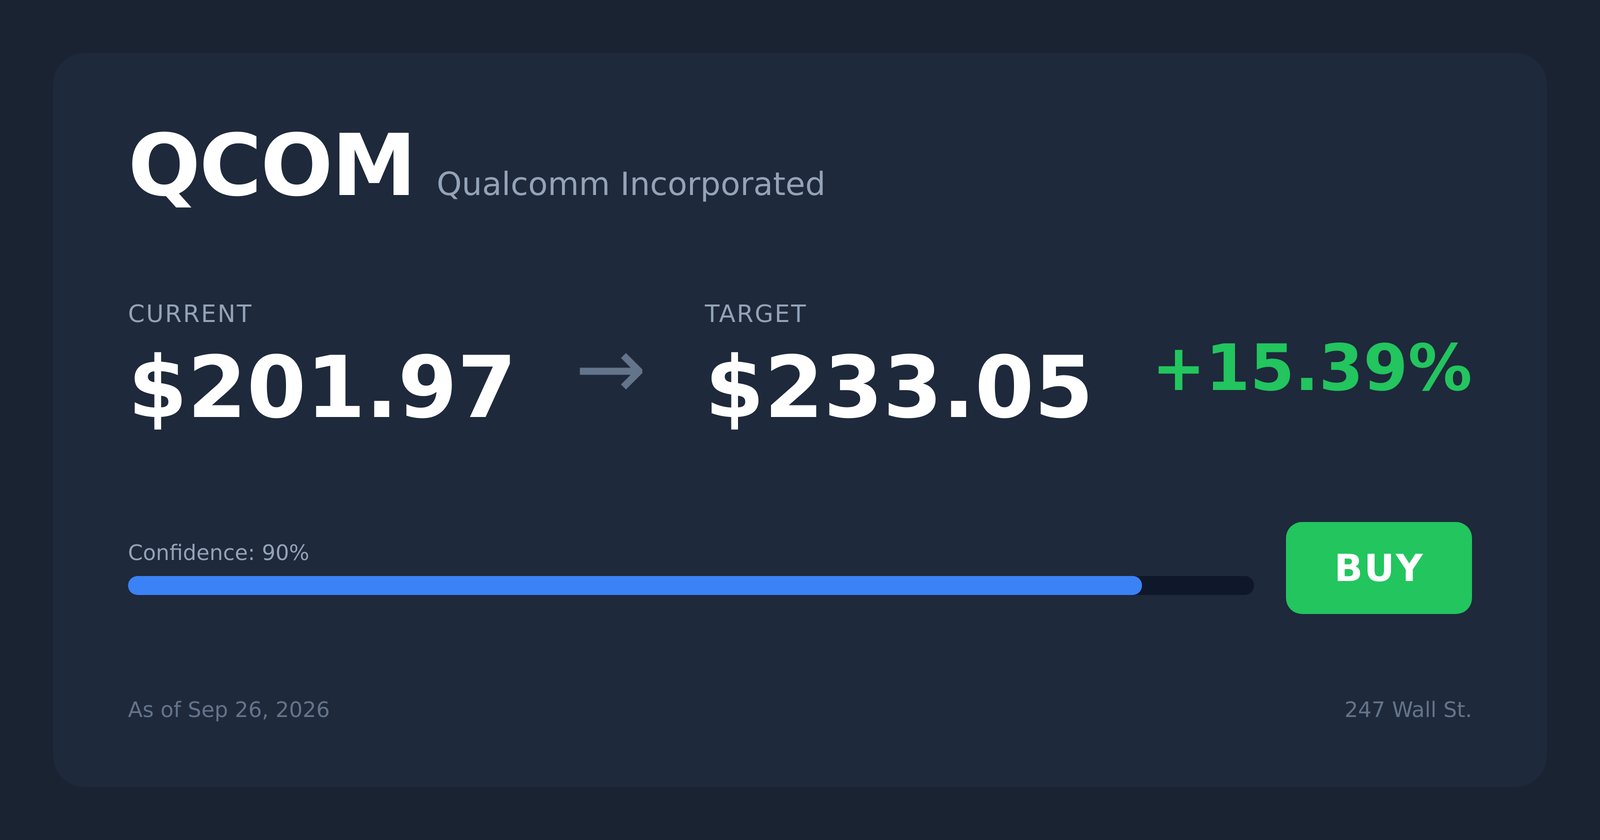
QCOM Price Target — 24/7 Wall St.What Just Happened With Qualcomm Shares
Qualcomm rallied 23.28% over the past month and 15.44% year to date, though it sits roughly 25% below its 52-week high of $257.56.
Fiscal Q3 2026 results showed revenue of $9.947 billion (beating estimates by 2.84%) with non-GAAP EPS of $2.21, missing consensus by 0.49%. Handsets fell 20% year over year, but automotive grew 61% to $1.588 billion, marking 23 consecutive quarters of double-digit growth.
Why Bulls See a Breakout to $245+
CEO Cristiano Amon raised the long-term non-handset target to $40 billion by fiscal 2029. Two hyperscaler custom silicon programs begin shipping in the December quarter, with the first high-bandwidth compute solution launching in mid-2027.
Automotive run-rate exiting fiscal 2026 was lifted to approximately $7 billion from $6 billion. Non-handset growth is guided to accelerate from 24% in fiscal 2026 to greater than 60% in fiscal 2027. If execution holds, the bull case reaches $245.07 within 12 months.
Learn 7 Ways To Generate Income With A $1,000,000+ Portfolio
If you’ve saved over $1,000,000, this guide is for you. The last thing you want in retirement is to run out of money, you want your money to generate lasting income while you enjoy your life.
Now you can learn the strategies wealthy retirees use to fund their retirement with The Definitive Guide to Retirement Income from Fisher Investments. Download the guide today! (sponsor)
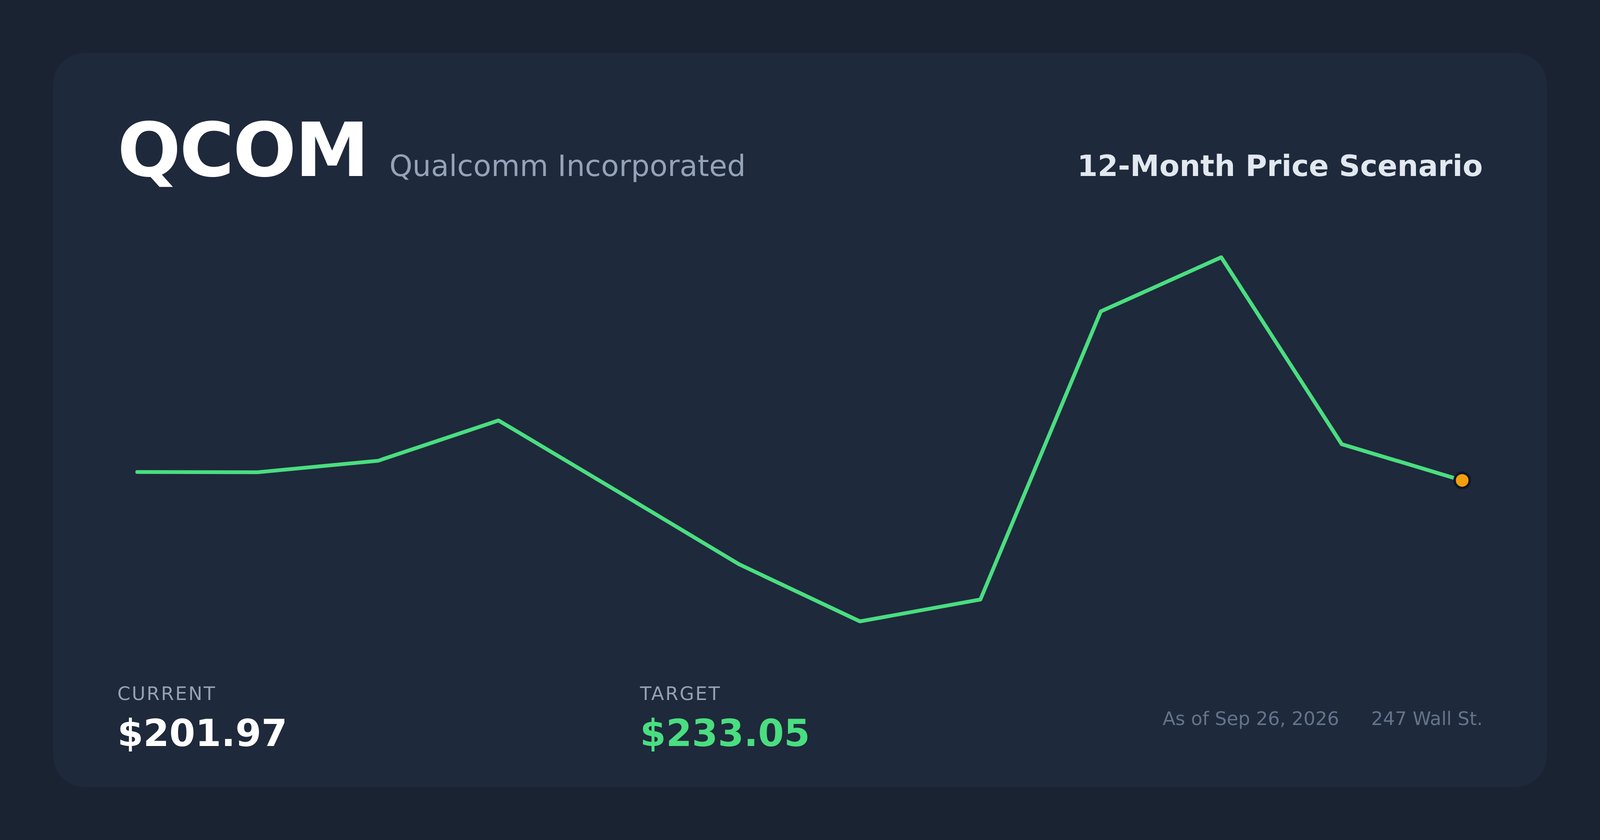
QCOM Price Scenario — 24/7 Wall St.What Could Go Wrong for QCOM
The bear case starts with Apple (NASDAQ:AAPL). Management expects Qualcomm's modem share in the upcoming iPhone to be materially lower than the prior 20% estimate, with Apple revenue projected to fall roughly 50% from September to December.
Add memory-driven input cost inflation, QCT gross margins slipping below the historical 48% to 50% band, and a 1.5% to 2% margin drag from initial data center ramps.
Q3 operating income fell 41.13% year over year. Bulls counter that management is pushing through double-digit price increases to recapture margin. Our bear-case 12-month floor is $192.71.
Advertisement
QCOM Analyst Ratings — 24/7 Wall St.How Qualcomm Compares to Broadcom and Marvell
Broadcom (NASDAQ:AVGO) is the aspirational benchmark. Broadcom's Q3 FY26 AI semiconductor revenue hit $16.7 billion, growing 221% year over year, with Q4 AI silicon guided to $21.7 billion.
At a $1.67 trillion market cap versus Qualcomm's roughly $207 billion, AVGO shows what the market pays for proven hyperscaler exposure. Qualcomm's data center revenue is aiming for a fraction of that, which is why our target treats the ramp cautiously.
Marvell Technology (NASDAQ:MRVL) is the closer analog. Marvell's Q2 FY27 data center revenue reached $2.17 billion, up 46% year over year and 79% of total revenue, with a Google custom silicon partnership tied to a warrant for up to 7% of Marvell shares.
Marvell trades at a $226 billion market cap on far less revenue than Qualcomm, which makes our $228.68 target look conservative if Qualcomm's hyperscaler wins scale similarly.
Data Center Optionality Anchors the Thesis
Our 24/7 Wall St. price target of $228.68 reflects a buy with 90% confidence.
The tipping factor is the non-handset inflection: management is telling us fiscal 2027 growth exceeds 60% off a diversified base, and the market is still pricing Qualcomm like a handset company.
The same data center buildout powering that inflection is lifting a broader set of suppliers, seven of which we profiled in a free report on the AI infrastructure trade here: 7 Stocks Powering the AI Boom. Watch for December-quarter guidance to confirm the hyperscaler ramp and pricing actions to stabilize QCT gross margin.
Year
24/7 Wall St. Price Target
2026
$202.89
2027
$230.33
2028
$254.24
2029
$282.74
2030
$297.47
These projections assume Qualcomm executes on its $40 billion non-handset target and hyperscaler custom silicon scales as guided. Upside or downside could result from Apple share loss, US-China trade actions, or HBC adoption pace after mid-2027.
Learn 7 Ways To Generate Income With A $1,000,000+ Portfolio
If you’ve saved over $1,000,000, this guide is for you. The last thing you want in retirement is to run out of money, you want your money to generate lasting income while you enjoy your life.
Now you can learn the strategies wealthy retirees use to fund their retirement with The Definitive Guide to Retirement Income from Fisher Investments. Download the guide today! (sponsor)
Contact editorial@247wallst.com for any questions or corrections.
Source: “AOL Money”
